For some people, finding life insurance isn’t straightforward. A health condition, mental health history, higher-risk occupation, travel or hobby can sometimes make getting cover more complicated. This can include people living with conditions such as cancer, diabetes, heart disease or mental health conditions, as well as those whose work or lifestyle requires a more specialist approach.
But being told ‘no’ before does not necessarily mean every insurer will reach the same decision. Depending on your circumstances, there may be other options to explore.
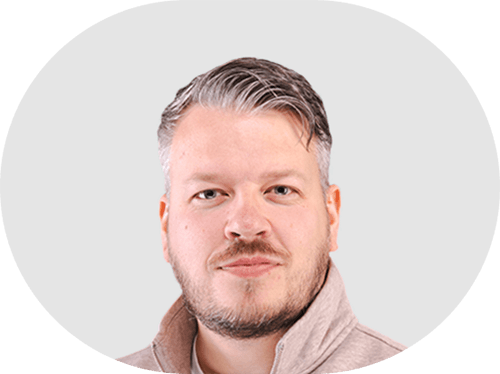
That’s where Tom Needham and LifeSearch’s Special Risk Team come in. Tom leads the team, which supports people who may have struggled to find life insurance or other protection cover before. The team takes the time to understand each customer circumstances and explore what options might be available.
For Tom, that expertise goes hand in hand with empathy. His approach is simple: there’s a real person behind every application, and everyone deserves the time, care and attention needed to understand their options.
“We protect others as you’d protect your own. If you’ve got somebody on the phone, that’s somebody’s mum, brother, uncle or grandma. You’d want them looked after if they were your own family.”
Tom NeedhamSpecialist Risk Expert
What Tom can help with
Tom and the LifeSearch Specialist Risk Team help people who:
- Have previously been declined for life insurance
- Have a medical condition or mental health history
- Need guidance on life insurance, critical illness cover, or income protection
- Work in higher-risk occupations
- Travel extensively
- Have hobbies that insurers may consider higher risk
The team takes the time to understand individual circumstances and explore what options may be available.
What makes Tom a Specialist Risk Expert?
Specialist risk often means looking beyond the obvious answer. Tom and his team build their knowledge by speaking directly with insurers and underwriters, keeping up with changing underwriting approaches and sharing what they learn from complex cases.
That means when someone has previously struggled to get cover, the team can take a closer look at their individual circumstances rather than assuming a previous decision will be the same everywhere.
Sometimes, it’s about taking the time to dig a little deeper, speaking with underwriters and understanding how different insurers assess health conditions, occupations and personal circumstances.
The team then shares those learnings with each other so that knowledge from one customer’s experience can help inform future conversations.
Taking the time to get it right
Many of the customers Tom’s team speaks to have circumstances that make finding cover more complicated, from medical conditions such as cancer, diabetes, heart conditions and mental health disclosures to higher-risk occupations, travel or hobbies.
Tom encourages his advisers not to rush these conversations. Sometimes that means splitting them over two calls, giving someone time to understand their options and consider what’s genuinely right for them.
Because for Tom, finding something isn’t the same as finding the right thing.
“I have no problem with somebody in my team saying, ‘this product isn’t appropriate for you’. It might be available, but if it isn’t right for that person and what they need, we need to say that.”
That might mean exploring a different level of cover, reviewing the position again in the future or explaining why an available option may not meet the customer’s needs. If cover costs more than expected, Tom also encourages his team to focus on what would genuinely make a difference and what the customer can comfortably afford over the long term.
While many referrals are about life insurance, Tom's team can also support people looking at critical illness cover or income protection where health, occupation or lifestyle circumstances add complexity to the application process.
“It’s about finding a tailored solution. We want someone to understand exactly what they’re paying for and why, and for that cover to still feel worthwhile and affordable months and years down the line.”
Customer case study: building trust through understanding
One experience that has stayed with Tom involved a couple he first helped several years ago. One of them was going through a gender transition, with treatment and surgery still ongoing, while there were also other medical and mental health factors to consider. At the time, fully underwritten cover wasn’t available, so Tom helped them find an alternative, non-underwritten option.
For Tom, it was also a learning experience. Rather than making assumptions, he was open about what he didn’t know, asked questions and made sure he understood how the customer wanted to be addressed.
That openness helped build trust. Several years later, once their circumstances had changed, the couple came back to Tom personally and he was able to help them both secure fully underwritten cover.
What stayed with Tom most was that they remembered how he had treated them the first time around and trusted him enough to return.
“Having somebody come back years later because they remember who you are is one of the biggest compliments you can get as an adviser.”
It’s an experience that sums up the approach Tom encourages across his team: don’t make assumptions, be willing to ask questions and always see the person behind the application.
Supporting people through difficult conversations
Working in specialist risk can mean hearing some incredibly difficult stories.
Tom is conscious of what that means not only for customers, but for the advisers supporting them. His team regularly handles sensitive conversations, particularly around serious illness and mental health, so looking after the people providing that support matters too.
If an adviser has a particularly difficult call, Tom encourages them to step away and take some time before speaking to their next customer.
It all comes back to one thing: remembering that every referral represents a real person.
“It’s easy to think of somebody as another referral or another application. They’re not. They’re a real person. Sometimes they’ve just had a harder run in life, and our job is to have a real conversation with them and do the right thing.”
What drives Tom
After more than a decade at LifeSearch, Tom still enjoys speaking directly with customers as well as leading his team.
For him, one of the most rewarding parts of advising is when customers return years later because their lives have changed. They might have bought a home, had a child or changed jobs, and they trust Tom enough to ask for his help again.
As a leader, he gets the same satisfaction from seeing his team succeed, both professionally and personally.
Ultimately, both sides of the job come back to people.
“I love my job. From an advice perspective, it’s having people come back because they trust you. From a leadership perspective, it’s knowing my people, knowing what matters to them and seeing them succeed.”
Supporting you to find the right protection
If you’ve previously been declined for life insurance, have a health condition or mental health history, or think your occupation or lifestyle could make finding cover difficult, don’t automatically rule yourself out. A previous decline doesn't necessarily mean every insurer will reach the same decision.
Depending on your circumstances, there may be options to explore. Speaking to Tom or one of his team members, can help you understand how different insurers may assess more complex circumstances, and what cover, if any, may be available.
Because, as Tom puts it: “You’re speaking to a human, and that human will listen.”
Speak to a LifeSearch adviser today to explore what life insurance, critical illness cover or income protection could be available to you.